Six Months To Use Non-barcoded Stamps

Six Months to use non-barcoded stamps
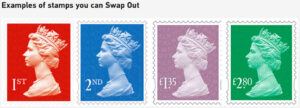
Many removals and storage companies still send quotes and follow up documents to customers in the post even after sending out emails. However, if you do have in your possession any non-barcoded everyday stamps – those with the Queen’s profile on – you have only six months left to use them up before they become worthless on 31 January 2023.

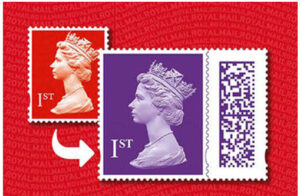
However, you can swap these stamps for barcoded versions for free through using the Royal Mail’s scheme. In February 2022, the Royal Mail announced that it will scrap ‘definitive stamps’, to many known as everyday’ stamps featuring the profile of the Queen against a plain background from 31 January 2023.  From this date you can only use barcoded stamps with the Queen’s profile on, or non-barcoded Christmas or special collection stamps that are issued by the Royal Mail.

If post is sent with non barcoded stamps from the 1st February 2023, the Royal Mail will treat the post as having insufficient postage.  This means that the person receiving the post may incur a surcharge, for removals quotes, this is not a great way to get a potential customer to book their removal with you. According to the Royal Mail website, sending a letter or large letter currently incurs a £2 fee where no postage has been paid at all.

Special issue stamps with pictures and images on and Christmas stamps can continue to be valid beyond January 2023 deadline. If you want more information and guidance  on which stamps you can exchange, see Royal Mail’s FAQs about definitive stamps.

Bar-coded stamps Information – https://www.royalmail.com/sending/barcoded-stamps
Mortgage Stress Test Scrapped

Bank of England scraps Mortgage affordability test also known as the Mortgage Stress Test Scrapped
Thousands of home buyers are potentially going to find it easier to obtain a mortgage from August 2022 as the Bank of England has scrapped the requirement of buyers to pass an affordability test. This move will allow many homebuyers to find getting onto the property ladder moving forward easier.
When it comes to freelancers and self employed, this move should in effect help them obtain mortgages from lenders. This move is not, as stated by the Central Bank, as a relaxation of the rules. Moving forward from the 1st of August 2022, new applications must be able to demonstrate that they would be able to cope with an increase rates should they to rise by 3%.
The original affordability test, also known as the ‘stress test’ was introduced after the financial crisis of 2007 – 2008 to counter act the reckless lending by some mortgage lenders that was attributed to the build-up of the crash. By introducing this test, it placed mortgage lenders to be more accountable to ethical lending and avoid the risky loans for home buyers that effected the stability of the financial markets.
One rule that is still in place by Bank of England is that the majority of new borrowing should stay within 4-5 times ‘the borrowers’ income in conjunctions with the guidelines and affordability criteria by the Financial Conduct Authority. The combination of this should deliver the level of resilience required for borrowing in the UK Financial System. As stated by the Bank of England, ‘these measures will bring resilience, but in a simpler, more predictable and more appropriate way.
6% of mortgage borrowers, claims the Bank, would have been able to secure larger home loans had the affordability test not been in place. In figures, this amounts to 36,000 individuals. With rising costs of living, this is viewed by many lenders and mortgage commentators as a very positive step to the market. This will allow many more home buyers get onto the property ladder and with larger mortgages. Borrowers must be able to demonstrate that they are able to accommodate the loan to income ratio value to ensure that they are able to secure the mortgage loan for their new home.
With property values continue to rise sharply, Barclays and The Halifax are amongst the lenders that are able to go to 5.5 times the loan to value ratio for high earning borrowers. Habito, is in some cases prepared to go up to 7 times the loan to value for some borrowers.
This is great news for the removals industry especially at a time when the fuel and energy costs combined with the food cost crisis. By making it easier for borrowers to get onto the property ladder and others already borrowing secure larger mortgages it should help keep the sector continue to move home owners across all areas of the property market.
.

Dodgy Damage Claims & Misleading Volumes

Dodgy Damage Claims and Misleading Volumes

I speak to at least a couple of Members every day. Normally they are calling me for advice or they have something to report that they think I should be made aware of.

I have learned from such recent conversations that a by-product of the squeeze on household budgets seems to be an increase in false allegations that the remover caused damage followed by the inevitable insurance claim.

It seems some customers are looking to recover some if not all of the move cost through insurance.

I have been in the removals industry for close to 40 years and believe me when I say false allegations of damage generally increase when money is tight so be alert to potential claims. That said you can reduce the likelihood of having to deal with such irksome nonsense if you take precautions,

My advice is to alert your crews to the problem and instruct them to photograph any item that is damaged before they move it. Video evidence can be even more powerful and one of our Member’s states on their quotation that they reserve the right to use video and record conversations during the move. The result is that since they implemented that procedure they haven’t been the victim of fraudulent damage allegations.

They also take videos if they arrive at collection address only to find they have been misled as to access or the volume items to be moved. If the move was quoted on the basis of a video survey they can then compare the video they take on move day with the survey video. Charging extra for a higher volume or long carries may be challenged but the challenge will be unsustainable given video evidence.

I hope this blog has been helpful.

Blog by Geoff Salt